Best Loan Apps in the Philippines (2026): Top Legit Picks
Updated: Sep 30, 2026
Written byRina Bernardo
More Filipinos than ever are turning to personal loan apps for everyday needs — tuition, medical bills, a business top-up, or bridging a gap before payday. But the market is crowded, and not every "loan app" you see on Facebook or Google Play is legitimate. Some operate without SEC approval, charge hidden fees, or use harassment tactics that are outright illegal. That's why it's important to compare your options carefully before you apply.
To help you make a more informed decision, we've ranked some of the best loan apps in the Philippines based on factors that matter most, including legitimacy, transparency, interest rates, approval speed, loan flexibility, customer experience, and overall value. Whether you're applying for an emergency loan or planning your next financial milestone, the right loan app should help you move forward with confidence, not add unnecessary stress.
How We Chose the Best Loan Apps
We evaluated each lender using several practical criteria to help readers compare their options fairly:
-
Legitimacy — active SEC registration and Certificate of Authority (CA), or BSP regulation for digital banks
-
Interest rate and fees — whether the true cost is disclosed upfront, with no hidden charges
-
Approval speed and disbursement — how fast the money actually lands in your account or wallet
-
Loan amount and term range — how much you can borrow and how long you have to repay
-
Requirements — what ID, income proof, or account history you need
-
App experience and support — how easy the app is to use and how responsive the support team is
-
Reputation — reviews, ratings, and complaint history
Best Loan Apps in the Philippines (2026)
Looking for a legitimate loan app with competitive rates? Here are some of the best options available today based on transparency, customer experience, flexibility, and overall borrowing value.
|
Loan app |
Loan amount |
Grace period |
Certification |
Cashback |
Available card options |
Fees |
App Rating (Google Play Store) |
App Rating (Apple Store) |
Interest rate |
|
Salmon |
₱3,000 - ₱250,000 |
Up to 62 days |
Cerise+SPTF Client Protection Certification – Silver Level |
0.5% cashback on eligible purchases |
Physical card Virtual card One-time virtual card |
No Annual fees Late payment fee: ₱300 Card fee: ₱199 |
4.8 |
5.0 |
9% |
|
Tonik |
₱5,000 - ₱50,000 |
Up to 31 days |
N/A |
N/A |
Physical card Virtual card |
Processing fee: ₱500 Late payment: ₱500 |
4.7 |
4.6 |
4.20% |
|
Maya |
₱15,000 - ₱250,000 |
Up to 15 days |
N/A |
N/A |
Physical card Virtual card |
Processing fee: 2.49% |
4.6 |
4.6 |
1.40% |
|
GCash |
₱500 - ₱125,000 |
Up to 7 days |
N/A |
N/A |
Physical card |
Processing fee: 3% to 5% of loan amount Late payment fee: 1%of loan amount + 0.15% of your total outstanding balance |
4.2 |
3.3 |
1.59% - 6.99% *based on your eligibility and chosen payment term |
|
Home Credit |
₱3,000 - ₱150,000 |
N/A |
N/A |
N/A |
Physical card |
Processing fee: ₱500 |
4.8 |
4.8 |
starts at 2.32% |
|
Cashalo |
₱1,000 - ₱25,000 |
5–7 days |
N/A |
N/A |
N/A |
Daily service fee: 0.2% Late payment: 5% |
4.7 |
4.6 |
0.2% daily |
|
JuanHand |
₱2,000 - ₱50,000 |
Up to 7 days |
N/A |
N/A |
N/A |
Processing fee: ₱0 |
4.7 |
4.6 |
0.025% daily |
|
BillEase |
₱2,000 - ₱40,000 |
Up to 2 days |
N/A |
N/A |
N/A |
Convenience fee: ₱25 |
4.6 |
4.7 |
3.49% |
|
Finbro |
₱1,000 - ₱50,000 |
Up to 15 days |
N/A |
N/A |
N/A |
Processing fee: ₱660 |
4.6 |
4.7 |
6% |
|
Tala |
₱1,000 - ₱25,000 |
~6 days |
N/A |
N/A |
N/A |
Processing fee: 3.99% to 9.99% Service fee: 0.21% to 0.43% |
4.8 |
N/A |
0.43% daily |
1. Salmon — Best Overall
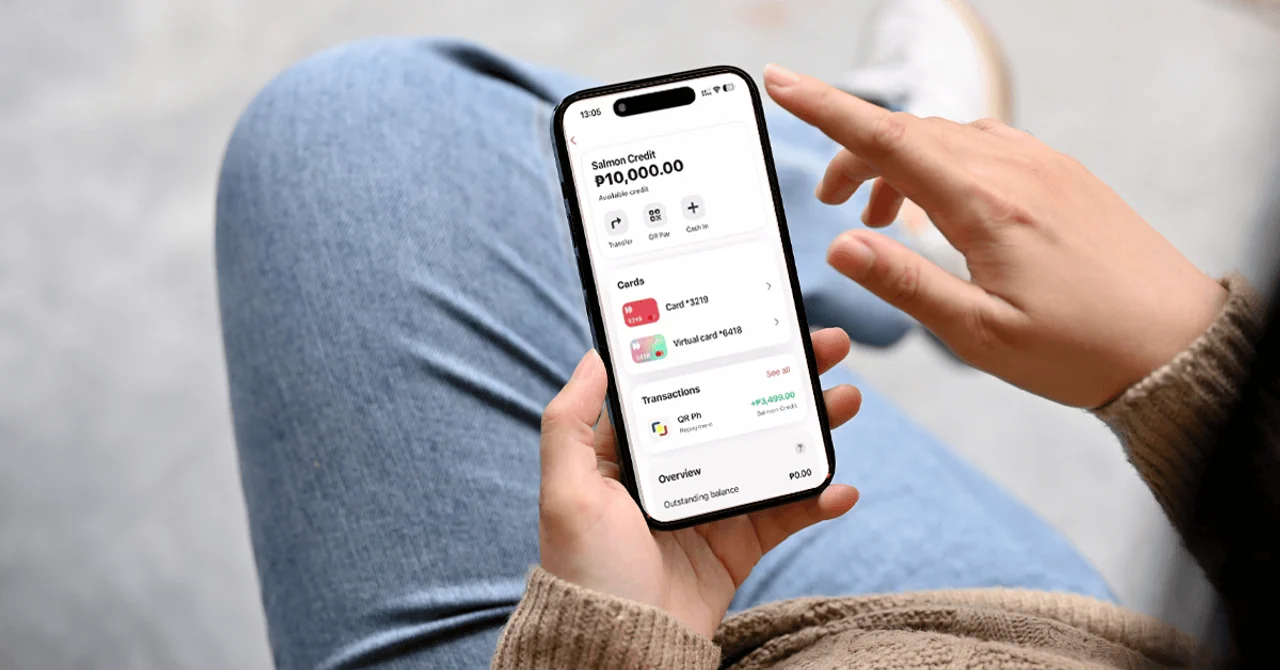
Salmon’s credit products combine borrowing convenience with a strong focus on security, transparency, and customer protection. It is offered by Salmon Finance, an SEC-regulated lender, which is held to strict standards of transparency and borrower protection. The company is also one of only six lenders in the Philippines to hold a Cerise+SPTF Client Protection Certification, an independent assessment that affirms its commitment to fair and responsible lending practices.
With a 4.8-star score on both the App Store and Google Play, the Salmon app is designed to make borrowing simple and seamless. Security features such as biometric login, two-step verification, and AI-powered fraud monitoring further ensure that the experience is not only convenient, but safe.
Best For: Borrowers who want a secure, convenient digital lending experience with flexible options for cash, credit, and product financing.
Pros:
-
Cerise+SPTF Client Protection Certified
-
Skip paying interest rate within grace period of up to 62 days
-
Multiple financing options in one app
-
Product loan available at 10,000+ partner stores
Cons:
-
High interest after grace period
-
Limited initial limits
2. Tonik
Tonik is a digital bank that offers personal loans, savings, and other banking products. Its Credit Builder loan allows users to borrow up to ₱50,000 with 6, 9, or 12-month payment terms. It's a suitable option for borrowers who prefer managing their finances within a single digital banking ecosystem.
Best For: Borrowers looking for larger personal loans through a digital bank.
Pros:
-
Digital application
-
Physical and virtual card available
-
Flexible repayment options
Cons:
-
Approval depends on eligibility
-
Loan offers vary per applicant
3. Maya
Maya Personal Loan is an unsecured digital cash loan of up to ₱250,000, with maximum limits reaching up to ₱400,000 for qualified accounts. It features monthly add-on rates starting as low as 0.77%, no collateral requirements, and fast fund disbursement directly to your Maya Wallet upon approval.
Best For: Existing Maya users who want to manage borrowing alongside their everyday financial transactions.
Pros:
-
Fast application
-
Quick disbursement
-
Flexible repayment options
Cons:
-
Strict evaluation
-
Loan offers vary per applicant
4. GCash
GCash offers several borrowing options within its widely used e-wallet. GLoan provides cash that can be used for different expenses, while GGives lets eligible users pay for purchases through installments at participating merchants.
Best for: GCash users who want borrowing options that connect directly to their wallet and everyday purchases.
Pros:
-
Multiple borrowing options in one app
-
Convenient for existing GCash users
-
GGives can be used for eligible installment purchases
Cons:
-
Not all lending features are available to every user
-
High processing fee
Related: GLoan, GGives, and GCredit: How to Avail of a Loan in GCash
5. Home Credit
Aside from product loans for items such as gadgets and appliances, Home Credit also offers cash loans for qualified borrowers up to ₱150,000. Its product financing can also be available to people who don't have a credit card.
Best for: Borrowers who need financing for major purchases or want both product and cash loan options.
Pros:
-
Established consumer financing platform
-
Availability across thousands of partner retail stores nationwide
Cons:
-
Product loans may require a down payment depending on the offer
-
Strict penalty fees
-
Debt collection practices have been subject to regulatory scrutiny, including concerns raised by the Securities and Exchange Commission (SEC)
6. Cashalo
Cashalo offers several ways to borrow, from short-term cash loans to purchase financing and Buy Now, Pay Later options. With loan amounts ranging from ₱1,000 to ₱25,000, this makes it an option for borrowers who want financing for different everyday needs.
Best for: Borrowers looking for smaller cash loans or installment financing for purchases.
Pros:
-
Quick disbursement
-
No hidden upfront deductions
Cons:
-
High interest and service fees
-
Strict penalty fees
7. JuanHand
JuanHand is a digital lending platform focused on providing Filipinos with convenient access to online cash loans with terms up to 12 months. Its app-based application allows borrowers to complete the process without visiting a physical lending branch.
Best for: Borrowers looking for a straightforward digital cash loan application.
Pros:
-
Quick and easy application
-
Flexible customer service channels
-
Straightforward borrowing process
Cons:
-
Debt collection practices have been subject to regulatory scrutiny
-
Small limits for first-time borrowers
Related: JuanHand Loan App Review: Should You Borrow Money from JuanHand?
8. BillEase
BillEase combines Buy Now, Pay Later financing with cash loans and other everyday payment features. Its platform can be useful for shoppers who want to split eligible purchases into installments without using a traditional credit card.
Best for: Online and in-store shoppers without credit cards and individuals needing manageable installment terms for gadgets or appliances.
Pros:
-
Quick registration and fast approval
-
Low monthly payments
-
Intuitive app
Cons:
-
High convenience fees
-
Some features limited to first-timers
9. Finbro
Finbro is a digital lending platform that focuses on online personal loans with a relatively simple application process. Its current platform allows qualified borrowers to apply online and receive loan proceeds through a bank account or e-wallet.
Best for: Borrowers looking for a fully digital personal loan with flexible repayment options.
Pros:
-
No collateral required
-
Easy online application
-
Fast approval
Cons:
-
Limited loan amount
-
High interest rates
Related: Finbro Loan Review: Things to Know Before You Borrow Money
10. Tala
Tala is designed for borrowers who need relatively small amounts quickly and want a simple application with minimal documentation. Qualified borrowers can apply through the Tala app using a valid ID, without needing collateral or traditional proof of income.
Best for: Borrowers who need a smaller amount for an urgent expense and prefer a simple digital application.
Pros:
-
Continuous access to loans
-
Access to Tala Wallet
-
Flexible loan terms
Cons:
-
Short repayment terms
-
0.43% daily interest rate
Loan Apps With Low Interest — What to Realistically Expect
A "low-interest" loan app isn't always the cheapest option. To find the best value, compare the total cost of borrowing — not just the advertised interest rate.
Different lenders calculate borrowing costs differently. Some advertise monthly interest rates, while others may show an annual percentage rate (APR) or highlight promotional offers that only apply to qualified borrowers. That's why it's important to compare the total amount you'll repay over the life of the loan.
When comparing loan apps, consider:
-
Interest rate
-
Processing fees
-
Late payment fees
-
Repayment period
-
Total repayment amount
Rather than looking for the "lowest" advertised rate, choose a loan that fits your budget and repayment capacity.
Monthly interest vs. APR: What's the difference?
A monthly interest rate shows the interest charged each month, while the annual percentage rate (APR) expresses the annualized cost of borrowing. They use different ways of presenting borrowing costs, so you shouldn't compare the percentages directly. Check the lender's total repayment amount and applicable fees to understand what you'll actually pay.
Related: For Your New Home, Travels, Emergencies, and More: 20 Personal Loans with Low Interest Rates
Fast-Approval & Quick Cash Loans
Many loan apps offer fast approvals, but approval and fund disbursement aren't always the same. While some applications are reviewed within minutes, the time it takes to receive your funds depends on the lender and whether your information is complete.
To help speed up your application:
-
Submit accurate information
-
Upload clear copies of your ID
-
Complete any required verification
-
Link your preferred bank account or e-wallet correctly
How to Spot a Legit Loan App (and Avoid Scams)
Before applying for any online loan, make sure the lender is legitimate. Taking a few minutes to verify a loan app can help protect both your money and your personal information.
Before submitting your application, check for these signs of a legitimate lender.
Verify the Lender's SEC Registration
The first and most important step is to check whether the company is legally authorized to operate in the Philippines. A legitimate lending or financing company should:
-
Be registered with the Securities and Exchange Commission (SEC)
-
Hold a valid Certificate of Authority (CA) to operate as a lending or financing company
-
Offer through a mobile app or website
However, SEC registration alone isn't enough. A company may be registered as a corporation but still lack the required authority to engage in lending activities. That's why it's important to verify both its corporate registration and its Certificate of Authority before borrowing.
You can verify a lender by checking the SEC's official database and reviewing its published advisories on authorized and unauthorized online lending platforms.
Watch Out for Upfront Payment Requests
Legitimate lenders generally do not ask borrowers to pay processing fees before releasing an approved loan. If you're asked to send money first before receiving your loan, treat it as a warning sign and verify the lender carefully.
Protect Your Personal Information
Many loan apps request access to certain information as part of the application process. However, be cautious if an app asks for permissions that don't seem necessary, such as unrestricted access to your contacts, photos, or other personal files without a clear explanation.
Review the app's privacy policy so you understand how your information will be used and protected.
Read Customer Reviews
Before downloading a loan app, check recent reviews on the App Store or Google Play. While no company receives perfect feedback, repeated complaints about hidden fees, poor customer support, or unfair collection practices may indicate issues worth considering.
The SEC has also flagged specific unregistered apps operating on Google Play, reminding the public these platforms are not authorized to offer or process loans — so checking the registry before you download anything new is worth the two minutes it takes.
Related: Borrower Beware: Loan Scams in the Philippines to Avoid
How to Apply for a Loan Through an App (step-by-step)
Most online loan applications follow a similar process. Preparing your documents ahead of time can make the experience faster and smoother.
Although application steps vary slightly by lender, here's what you can generally expect.
Step 1: Download the Official App
Only download loan apps from trusted sources such as the Google Play Store or Apple App Store. Double-check that you're installing the official application published by the lender.
Step 2: Create an Account
Register using your mobile number or email address and follow the account verification process. Some lenders may require one-time password (OTP) verification.
Step 3: Complete Your Profile
You'll typically be asked to provide:
-
Personal information
-
Address
-
Employment details
-
Income information (if required)
Provide accurate information to help avoid delays during evaluation.
Step 4: Upload Your Documents
Most lenders require at least one valid government-issued ID. Depending on the loan product, you may also need proof of income or supporting documents.
Step 5: Choose Your Loan Amount and Repayment Term
Review your available loan offer carefully. Before accepting, check:
-
Monthly payment
-
Total repayment amount
-
Interest charges
-
Applicable fees
-
Repayment schedule
Step 6: Wait for the Lender's Decision
Once your application is submitted, the lender will review your information. If approved, you'll receive details about your loan offer before accepting the agreement.
Step 7: Receive Your Funds
Depending on the lender, funds may be sent to your:
-
Bank account
-
E-wallet
-
Linked financial account
Requirements for Online Loans in the Philippines
Common requirements include:
-
At least 18 years old (some lenders require applicants to be older)
-
A valid government-issued ID
-
An active Philippine mobile number
-
A working email address
-
Proof of income for certain loan products
-
An active bank account or e-wallet for fund disbursement
Most loan apps have similar basic requirements, although eligibility varies by lender and loan product. Some lenders may also consider factors such as employment status, repayment history, or internal credit assessment before approving an application.
Make Your Next Borrowing Decision With Confidence
The best loan app isn't simply the one with the fastest approval — it's the one that offers transparent terms, responsible lending, and a borrowing experience that fits your needs.
Among the loan apps we reviewed, Salmon stands out as our top overall pick for its straightforward application process, customer-focused experience, and flexible financing options. Still, the right choice depends on your financial situation and repayment capacity.
Before you apply, compare loan costs carefully, understand the repayment terms, and borrow only what you can comfortably repay.
Frequently Asked Questions
What is the best legit loan app with low interest?
The best loan app depends on your financial needs, borrowing amount, and repayment preferences. However, compare the total borrowing cost and any applicable penalties. The right loan should be affordable and manageable based on your budget.
Is Salmon loan app legit?
Yes. Salmon Credit Line and Product Loan are offered by Salmon Finance Inc. (SEC Reg. No. CS201916698, C.A. No. 1241) through its licensed OLP, Salmon Finance. Salmon Finance also holds a Cerise+SPTF Client Protection Certification, reflecting its commitment to fair and responsible treatment of borrowers.
What are the requirements to borrow from a loan app?
Requirements vary by lender, but most loan apps ask for a valid government-issued ID, personal information, an active mobile number, and, in some cases, proof of income.
How fast can I get approved for an online loan?
Approval times differ depending on the lender and your application. Some loan apps can review applications within minutes, while others may take longer if additional verification is required.
What loan apps are approved/registered with the SEC?
Salmon, Cashalo, BillEase, JuanHand, Tala, and Finbro all hold active SEC registration and Certificates of Authority. Tonik, Maya, and GCash's GLoan operate under BSP regulation through their bank partners.
Can I get a loan app with low interest and a long term?
Some lenders offer longer repayment terms, but eligibility depends on factors such as the loan amount, your financial profile, and the lender's assessment. Compare several options before making a decision.
Are there loan apps for students?
Some lenders may accept applicants with alternative sources of income, while others require stable employment. Review each lender's eligibility requirements before applying.
About the author
Rina Bernardo
Rina is a Senior Associate for Content Strategy with nearly a decade of experience across the content landscape, having worked as a writer, editor, and team lead. Her background spans multiple industries, including eCommerce, travel, and real estate, where she has developed a strong eye for storytelling and audience engagement. Outside of work, Rina enjoys running, reading books, journaling, and experimenting with new iced coffee recipes.
Related articles